This article was authored by Kayla Johnson, Financial Planning Associate.
Planning for retirement involves a lot of considerations – replacing your working income, navigating a sustainable withdrawal rate, planning for healthcare costs and long-term care, estate and legacy planning, as well as tax and gifting strategies (RMD-leveling, withdrawal sequencing, Roth conversions, and qualified charitable distributions) can quickly become complex.
That’s why when it comes to generating an income from your retirement portfolio, simplicity is your friend.
At Pathfinder, the first step we generally recommend is to keep about one year’s worth of spending, that isn’t supplied by income streams like Social Security and pension, in an ultra-conservative investment. This can be advantageous to offset short-term market volatility. This provides a buffer that helps prevent needing to sell during unexpected market volatility if you need quick cash.
Next, we typically recommend using tax-deferred money to fund your regular monthly expenses so you can plan your federal and state tax withholdings correctly. Discretionary and supplemental cash needs can be funded with your non-retirement accounts. You still need to be careful when deciding what and when to sell, as the cost basis and holding period for each position will impact your taxes. Your non-discretionary and discretionary lifestyle expenses will often be funded with a combination of tax-deferred and taxable money, balanced based on careful tax planning.
Once your cash position is in place, and you’ve got a tax-advantageous funding strategy for income, you’ll need to create a plan to periodically refill your cash reserves to maintain adequate funding. This is where careful management of your investment portfolio becomes critical to determine a sequence of withdrawals across your varying account types.
Often, the largest portion of a retirement portfolio comes from tax-deferred retirement accounts, and because 100% of that money is taxable upon withdrawal, you’ll need to monitor your tax situation closely. Unexpected withdrawals from IRAs and 401(k)s can dismantle a great tax strategy, which is why we typically recommend using those accounts for planned expenses. Taxable funds are usually best used next, if the tax planning merits it. Finally, taking tax-free withdrawals from Roth IRAs and Health Savings Accounts (HSAs) for healthcare costs, is usually most advantageous to access last, particularly for unexpected expenses. However, in higher income years, it may be warranted to withdraw from these accounts first and change your regular distribution strategy.
These guidelines are good rules of thumb, but each year of retirement should be managed with the following in mind:


Landfall Home Sale Shatters Community's Previous Price Record
Cece Nunn
-
Nov 9, 2026
|
|
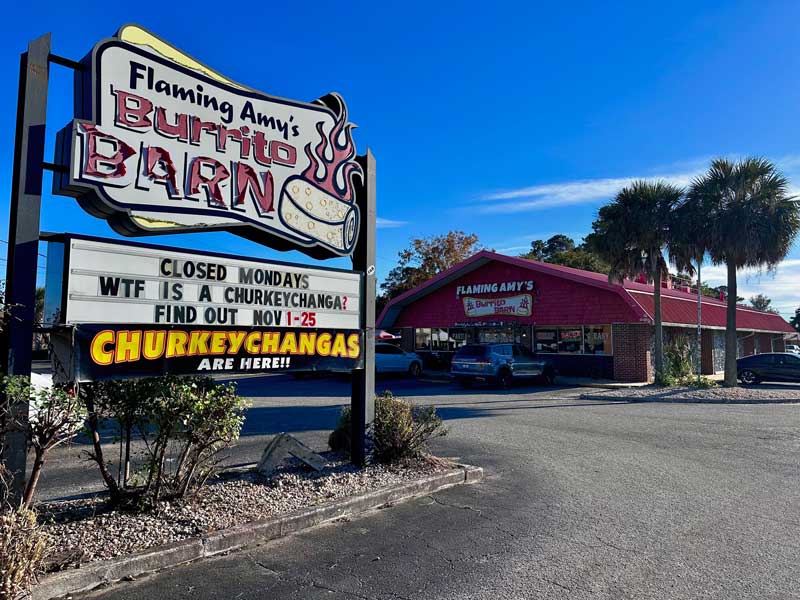
On Oleander Drive, Flaming Amy's Building Listed For Sale, Ground Lease
Emma Dill
-
Nov 10, 2026
|
|
Wilmington Developer Takes First Video Game To Market
Cierra Noffke
-
Nov 10, 2026
|
|
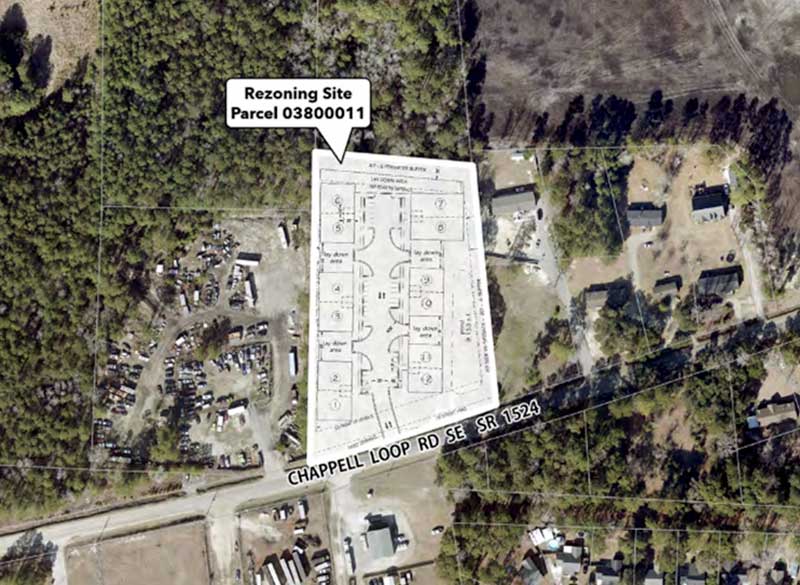
Flex Space Project Pitched Near Leland
Emma Dill
-
Nov 9, 2026
|
|
Paterson Joins Margaret Rudd & Associates Inc. Realtors
Staff Reports
-
Nov 10, 2026
|
|
The nominations for this year’s award finalists highlighted heroic moments, from small but important moments to community-changing deeds....
"Wilmington is a growing market for senior living; there’s strong demand,” said Pierce Carey, executive director of Porters Neck Village, a...
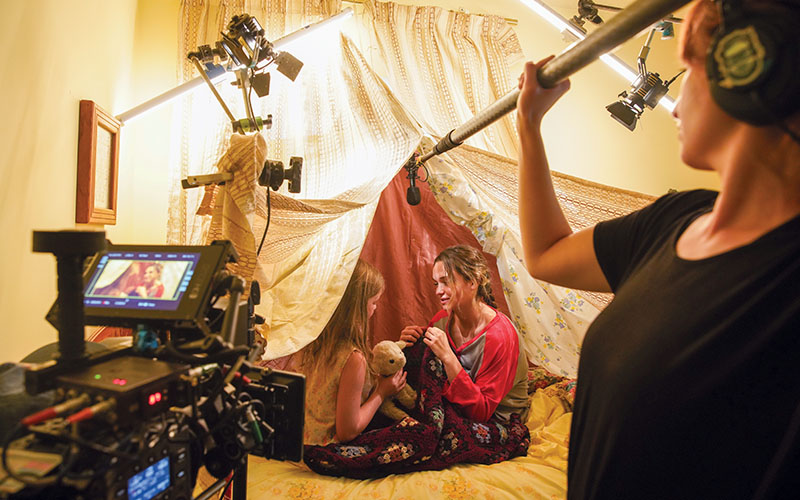
In October, Sen. Mike Lee said he believes state lawmakers could consider legislation allocating an additional $31 million for the film gran...
The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.