Follow Patrick Linkedin Facebook
Email Patrick Email
Financial
Aug 31, 2017

Six Ways Bad Credit Can Ruin Your Life

Sponsored Content provided by Patrick Stoy - Mortgage Consultant/Owner, Market Consulting Mortgage

Okay, using the word, “ruin,” in terms of what a bad credit score can do to your life may be a bit of an overstatement. 

It is probably more accurate to say that bad credit can produce a nasty hiccup, necessitate a detour or a create a pothole on the road of life.

The subject came up recently when I was talking with an older friend of mine, a homeowner with several investment properties, a vacation home and a number of classic cars that were all purchased with cash. She had a simple question – Why should I care whether I have good credit? I am definitely not trying to buy any more property.

Most people understand that there is a need for a good credit score if seeking to obtain financing for a home. This is a situation in which having bad credit could cost you thousands, or even tens of thousands, of dollars. Rest assured that lenders will thoroughly review your credit score and credit history during the mortgage application process. The worst-case scenario is your application for a loan could be denied if you have poor credit.

The other ways bad credit can seriously impede your quality of life and drastically reduce your ability to be financially solvent are not quite as obvious. 

The list below contains a number of items that can get pricey or unattainable if your credit is less than positive:

  • Credit cards – Interest rates on credit cards can range between seven and 36 percent. A good credit score can land you anywhere from 10 to 19 percent. With a bad credit score, the baseline interest rate can start at 22 percent and go up from there. This can make a huge impact, especially if you carry a balance.
  • Car insurance – It is a surprise for many people to learn that insurance carriers in 47 states review an applicant’s credit score before deciding on a rate. The result is that you could have higher-than-average rates for years to come. Certain carriers may not even approve you for insurance coverage at all if your credit score is extremely low.
  • Searching for employment – Believe it or not, it is legal for a potential boss to analyze your credit report, as long as you approve it in writing. This type of information can be used for the basis of making decisions about hiring, and it’s permissible under the Fair Credit Reporting Act. After all, many types of employers - such as banks, jewelry stores, credit card companies, etc. - face a significant amount of risk from theft, so it is easy to see their logic in deeming a candidate unworthy because of items on a credit report. However, some states have laws that limit the use of credit information in the hiring process.
  • Cell phone plans – Similar to car insurance providers, cell phone companies will check your credit prior to activating their service. If you have poor credit, it’s possible you will pay more each month for a phone or plan.
  • Car loans – Without a good credit score, it may be difficult to secure financing for a car. Those who are able to get a loan with a bad credit score could end up paying up to two percentage points more than someone with stellar credit.
It is worthwhile to point out that, even if your credit is less than perfect, it may be possible to obtain financing for a home. Also, there are occasionally small issues or discrepancies on a credit report that can be resolved with something as trivial as a phone call. Taking care of these can make an individual’s credit score jump immediately. For a consultation about your ability to secure financing or to obtain a letter of prequalification, give me a call at the number below.

Patrick Stoy (NMLS Numbers 39527 and 39166) has 18 years of mortgage lending experience. Patrick is CEO of Wilmington-based Market Consulting Mortgage, which he started in 2005 with a mission to build lifelong customer relationships by providing real value. To learn more about Marketing Consulting Mortgage, visit www.macmtg.com. Patrick can be reached at [email protected] or 910-509-7105.


Other Posts from Patrick Stoy

Mcm 14jan insight
Ico insights

INSIGHTS

SPONSORS' CONTENT
Morton300x300

Community College in Action: A Success Story

Jim Morton - Cape Fear Community College
Ccoudrietheadshot 942542742

Partnership Brings Groceries and Prescription Medications to Underserved Households

Chris Coudriet - New Hanover County Government
Ba1e4a78 34b5 4083 938e 2d270f78d36b2

De-Escalation: The Missing Link in Workplace Safety and Team Performance

Bill Praschak - Fully Loaded Defense LLC

Trending News

Tech Wilmington: Upcoming Events Calendar

Staff Reports - Oct 21, 2026

Live Oak Bank Reports Q3 Revenue Growth

Cierra Noffke - Oct 22, 2026

Corning Moves Forward With Wilmington Expansion

Cierra Noffke - Oct 21, 2026

Under New Owner, Pour Taproom To Add More Nonalcoholic Beverages, Events

Emma Dill - Oct 21, 2026

Vantaca, Live Oak Bank Chart AI Strategies

Cierra Noffke - Oct 20, 2026

In The Current Issue

Restaurants Keep Cooking In Tough Times

Mitchell is facing many of the same struggles as other restaurants. Despite the challenges, Mitchell said she won’t compromise on food quali...

Hemp Industry Caught In Legal Weeds

Uncertainty hangs over the hemp industry, including businesses in Wilmington that depend on the sale of hemp-based THC products....
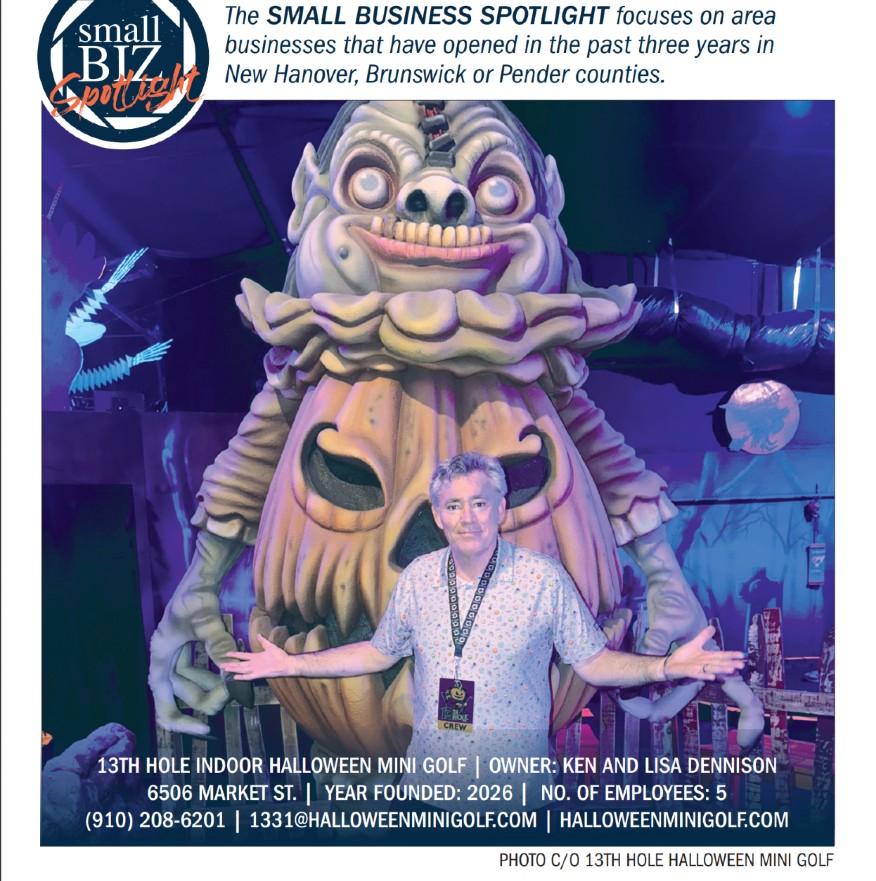

Small Business Spotlight: Halloween Mini-golf Owners Aim To Scare Up Year-round Fun

“Our vision is to create a mini-golf experience that becomes a welcoming space for everyone who enjoys a fun adventure with friends and fami...
Book On Business

The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.

Order Your Copy Today!


Galleries

Videos

2024 Power Breakfast: The Next Season