It’s no secret that financial markets don’t like surprises.
Unexpected changes and uncertainty can often lead to volatility and rapid fluctuations. The victory of Donald Trump was a stunner for everyone and a perfect example of this phenomenon, as it exerted an immediate and significant impact on interest rates and the stock market.
Politics aside, I think most home buyers probably shared a collective, nonpartisan groan of dismay after finding out lenders had increased their conforming fixed rates for a 30-year loan between 0.375 percent and 0.5 percent in a mere matter of days.
This may not seem like a big difference, but even a small change can have a huge impact on purchasing power, as well as the amount of money a borrower ends up spending over the life of a loan. In a scenario with a loan amount of around $425,000, the difference between the monthly payments for a loan at 3.75 percent and a loan at 4.25 percent would be about $125 - more than $10,300 over the first seven years.
Not surprisingly, many people are experiencing a great deal of frustration about the potential for their monthly payment to climb so quickly. If I had to go out on a limb, I would say that part of the reason for the frustration is there is no easy explanation for why interest rates have shot up so fast.
Many experts believe Donald Trump will reform the tax code and push through investments in our infrastructure in an effort to stimulate the economy. A growing economy would drive prices up across the board, creating an inflationary market environment. The interest rates and fees associated with mortgages are tied to mortgage-backed securities, which in turn are designed to be closely aligned with the 10-year Treasury rate. When investors expect an inflationary market environment, interest rates and fees tend to rise because they want to know that their funds will be protected.
This may be a bit of an oversimplification, but the takeaway is there is a general consensus that interest rates are going to continue increasing over the near-term. So, how is it possible to save money when inflation is a factor and interest rates are rising?
An effective strategy for avoiding a higher monthly payment and overall cost could be to opt for an adjustable rate mortgage (ARM) instead of a conventional 30-year fixed. I know, Dad said to always go for the 30-year fixed rate. Considering it is generally possible to get a no-cost, seven-year ARM at approximately ½ percent lower than a 30-year fixed, with a lower credit score, it may be time to put that conventional wisdom aside.
As I mentioned above, half of a percent can make a substantial difference. Being able to save more than $10,000 over the first seven years before the rate adjusts sounds like a good thing to me.
Plus, there is no guarantee the rate will adjust upward at the end of the term, contrary to what the pessimists would have you believe. Many folks have told me that their ARM actually decreased after the first seven years.
Of course, there is no way to know the future with any degree of certainty. There is no strategy that works for everyone or a one-size-fits-all approach to assessing a borrower’s options for obtaining financing. A computer can tell you what you qualify for and the various loans available but it will not be able to help you figure out the best possible solution to fit your individual circumstances and needs.
For a consultation about the various loan options available to you, please contact me at the number below.
Patrick Stoy (NMLS Numbers 39527 and 39166) has 16 years of mortgage lending experience. Patrick is CEO of Wilmington-based Market Consulting Mortgage, which he started in 2005 with a mission to build lifelong customer relationships by providing real value. To learn more about Marketing Consulting Mortgage, visit www.macmtg.com. Patrick can be reached at [email protected] or 910-509-7105.


Tech Wilmington: Upcoming Events Calendar
Staff Reports
-
Oct 21, 2026
|
|
Live Oak Bank Reports Q3 Revenue Growth
Cierra Noffke
-
Oct 22, 2026
|
|
Corning Moves Forward With Wilmington Expansion
Cierra Noffke
-
Oct 21, 2026
|
|
Under New Owner, Pour Taproom To Add More Nonalcoholic Beverages, Events
Emma Dill
-
Oct 21, 2026
|
|
Vantaca, Live Oak Bank Chart AI Strategies
Cierra Noffke
-
Oct 20, 2026
|
|
Mitchell is facing many of the same struggles as other restaurants. Despite the challenges, Mitchell said she won’t compromise on food quali...
Industry professionals say people seem much more willing these days to travel to the Wilmington area outside of the traditional summer vacat...
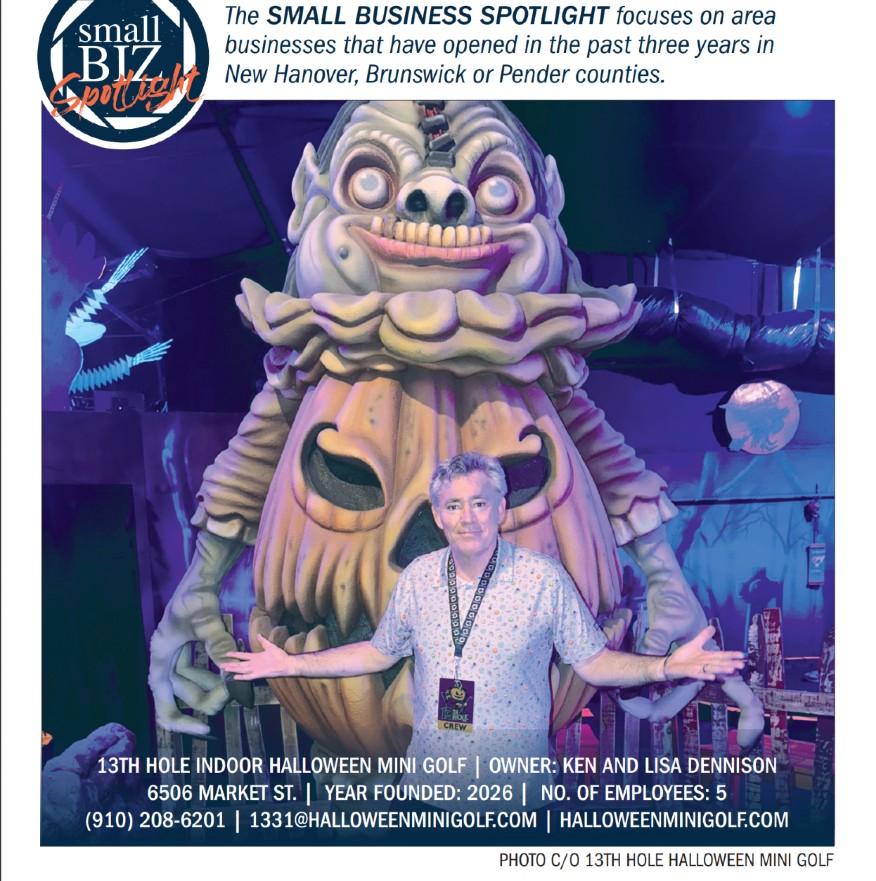
“Our vision is to create a mini-golf experience that becomes a welcoming space for everyone who enjoys a fun adventure with friends and fami...
The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.