Follow Patrick Linkedin Facebook
Email Patrick Email
Financial
May 15, 2017

New Guidelines Offer Forgiveness for Past Financial Troubles

Sponsored Content provided by Patrick Stoy - Mortgage Consultant/Owner, Market Consulting Mortgage

Time was ticking away. I had some turnovers that day and my shot—usually reliable, sometimes infallible—just wasn’t working. 

My coach pulled me aside and said, “Just get out there and go for it. The past doesn’t matter. Everybody makes mistakes, that’s why pencils have erasers.”

Needless to say, that was a moment from childhood that stuck with me, and it seems especially relevant to the new seasoning requirements for people who have faced a foreclosure, bankruptcy or short sale. People deserve a second chance sometimes, but the forgiveness is not unconditional. There are some guidelines and requirements that borrowers with a short sale, foreclosure or bankruptcy on their credit report have to meet in order to qualify for the purchase of a home or an investment property.  

For some of the major lending institutions, the seasoning requirements for various types of mortgage loans available to real estate buyers and investors are:

  • Conventional – The guidelines to obtain a conventional loan are among the most stringent. Borrowers with a foreclosure on their record will have to wait seven years from the date of completion. Those with a bankruptcy in their past will have to wait a minimum of two years from the date of discharge, and four years from the dismissal date. Buyers with a history of a short sale have to wait four years from completion.
  • FHA – The requirements to secure an FHA loan are not as severe. Three years is the magic number for borrowers with a foreclosure on their record. Buyers with a Chapter 13 bankruptcy in their background will need to show satisfactory payment performance over the course of a year and also obtain permission from the court. Those with a Chapter 7 in their past will need to wait two years from discharge. For borrowers with a short sale, there is no seasoning period, provided they have made all their payments on time for the 12 months prior to the short sale, and made all their payments on time for the 12 months preceding the loan application for the new mortgage.
  • VA – Borrowers with a foreclosure in their past will have to wait two years. The guidelines for those with a bankruptcy are the same as with FHA. Those with a short sale in their past will have to wait two years.
  • USDA – The guidelines for USDA borrowers are exactly the same as with VA, except the seasoning policy for borrowers with a foreclosure is three years instead of two.
  • Jumbo – Borrowers with a prior credit issue will have to wait seven years.
  • Fresh Start – As the name implies, this loan has the least stringent guidelines. There is no seasoning requirement for borrowers with a foreclosure, bankruptcy or short sale in their past.
  • Homeowner’s Access – This is another loan with guidelines that are not as strict as many other options. In general, borrowers who have experienced a credit problem in the past will have to wait two years before securing this type of loan.
There are many financing options out there for those who have face a short sale, foreclosure or bankruptcy, and there is almost always a solution available for even the most complicated obstacle. For a discussion about your options, please contact me at the number below.    

Patrick Stoy (NMLS Numbers 39527 and 39166) has 16 years of mortgage lending experience. Patrick is CEO of Wilmington-based Market Consulting Mortgage, which he started in 2005 with a mission to build lifelong customer relationships by providing real value. To learn more about Marketing Consulting Mortgage, visit www.macmtg.com. Patrick can be reached at [email protected] or 910-509-7105.

Other Posts from Patrick Stoy

Mcm 14jan insight
Ico insights

INSIGHTS

SPONSORS' CONTENT
Geoff21 6292624148

Passing the Torch: Bringing Estate Planning and Business Succession Together

Geoffrey Losee - Losee Coggins LLP
Untitleddesign7

Five Years After Surfside: What HOA Boards Can Learn About Structural Integrity and Long-Term Planning 

Dave Orr - Community Association Management Services
Untitleddesign13 162533932

Ready to Sell Now? Maybe You Don’t Have to Wait

Tully Ryan - IQEXIT

Trending News

Tech Wilmington: Upcoming Events Calendar

Staff Reports - Oct 21, 2026

Live Oak Bank Reports Q3 Revenue Growth

Cierra Noffke - Oct 22, 2026

Corning Moves Forward With Wilmington Expansion

Cierra Noffke - Oct 21, 2026

Under New Owner, Pour Taproom To Add More Nonalcoholic Beverages, Events

Emma Dill - Oct 21, 2026

Vantaca, Live Oak Bank Chart AI Strategies

Cierra Noffke - Oct 20, 2026

In The Current Issue

Election 2026 Q&A: N.C. Senate Candidates Share Their Views

Among the races this year is the contest between incumbent Sen. Michael Lee, R-New Hanover, and newcomer Jessica Bichler for N.C. Senate Dis...
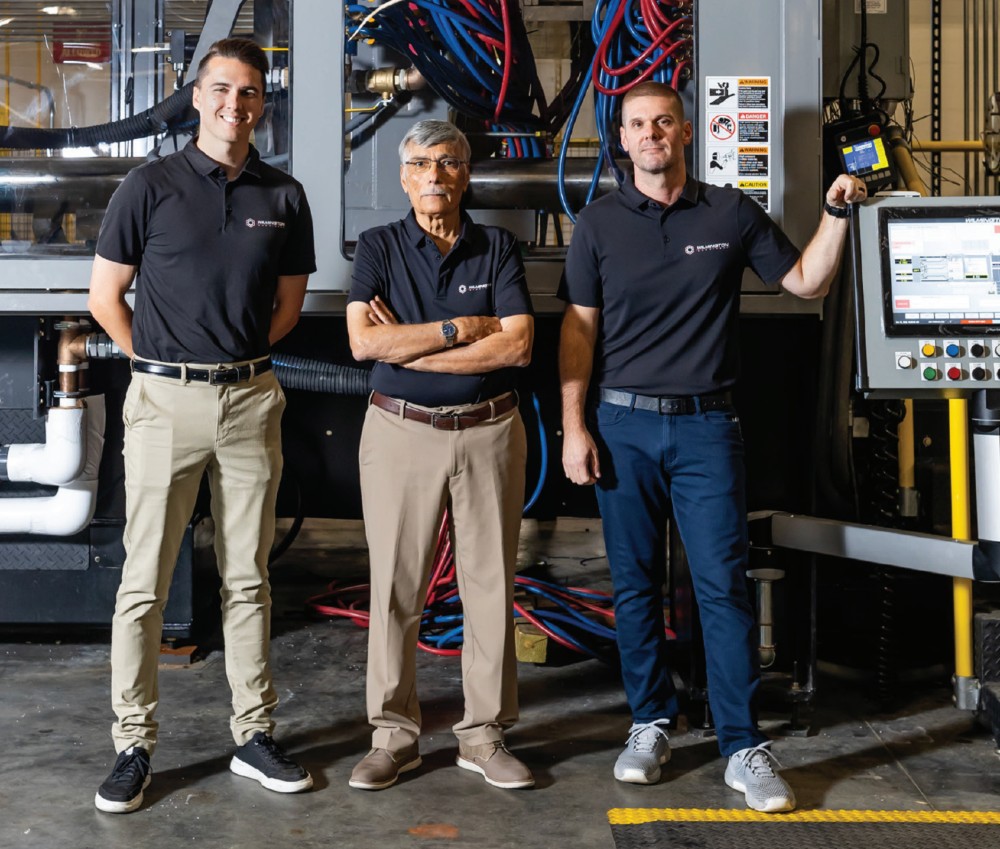

Machine Firm Molds Plan For Growth

Now under the ownership of Yousry Sayed, the founder of Quality Chemical Laboratories, Wilmington Machinery is eyeing business growth....
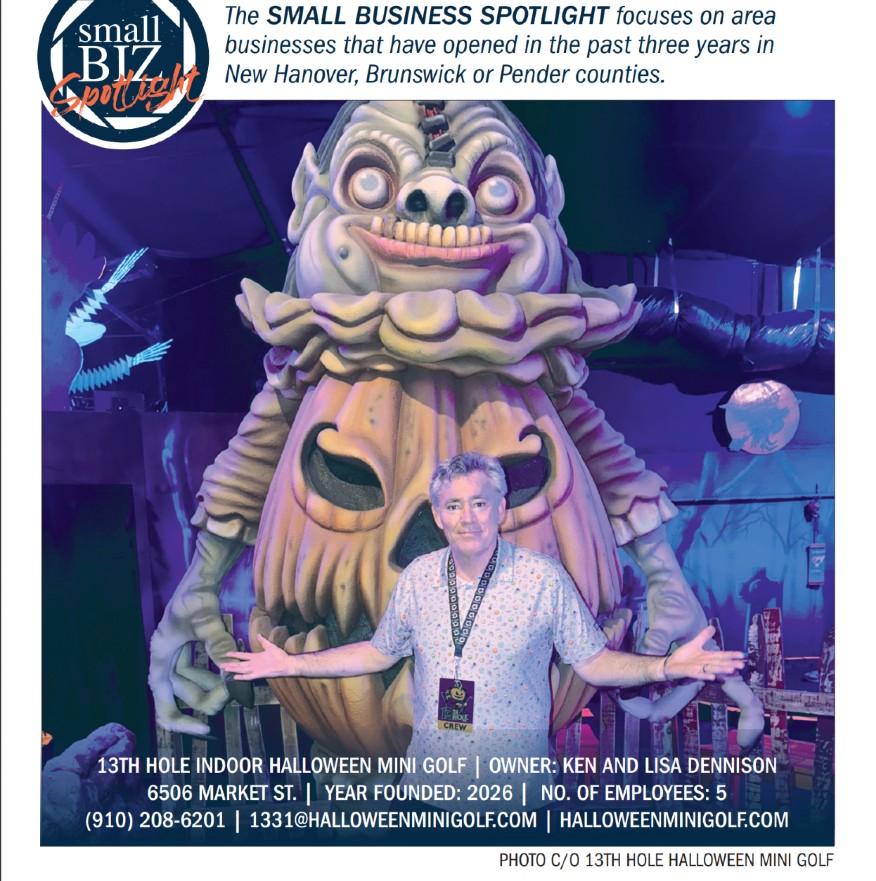

Small Business Spotlight: Halloween Mini-golf Owners Aim To Scare Up Year-round Fun

“Our vision is to create a mini-golf experience that becomes a welcoming space for everyone who enjoys a fun adventure with friends and fami...
Book On Business

The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.

Order Your Copy Today!


Galleries

Videos

2024 Power Breakfast: The Next Season