I am fortunate to have worked with many small businesses here in Wilmington and across North Carolina over the last 25 years. I have watched many of them grow and prosper, some far beyond what they ever could have imagined when they started out.
When a business really takes off, it’s easy for the owner to get wrapped up in the excitement, as well as the increasing demands on their time. But as a business grows, its financial needs do too, so it’s important to stay in touch with your banker, who can make sure your financial services are keeping pace with your growth.
Oftentimes, the financial tools you used to start your business are not as appropriate or helpful once your business is well-established and growing. For example, many small business owners I’ve worked with have used their personal checking account or line of credit to get their business up and running. However, once the business has established its own track record and credit history, there are other options available that can save the owner money and time.
A few of those considerations include:
- Stop borrowing on your personal line of credit. Many new entrepreneurs borrow on their credit cards or take out a home equity loan for startup dollars. Now that you are established, look for small business lines of credit and loans that will be more beneficial. By obtaining a line of credit in the business name, you can pay off the business debt on the personal credit cards, which can bring down your credit score. If you improve your score, you will qualify for lower interest rates on business and consumer items. Interest rates on business lines of credit are usually lower than with credit cards, excluding special offers. Take advantage of the opportunity to establish credit in your business' name.
- Find the best checking product for your needs. Now that your business is growing up, you may no longer need your personal checking account for your business. Look for a business checking account tailored specifically for small business that recognizes the number of deposits and checks you may need to write as your business grows. You should also consider a bank’s technological capabilities to be sure you have the most advanced tools, including remote deposit, electronic payments, et cetera, that can make managing your company’s cash flow much easier and more efficient.
- Re-examine your merchant services relationship. When you first launched your business, the number and dollar volume of its credit card transactions were probably much lower than they are today. You may have had to use a sub-prime provider for merchant services and found yourself paying twice the going rate. Now that your business is established and you have a good credit rating, shop for a merchant services provider with a more competitive price.
I find that many small business owners are surprised and excited when they can run their business even more efficiently by utilizing new tools they hadn’t yet considered. As a business grows, it’s important to be aware of those opportunities, which comes from frequent reviews of your financial statement with your banker and other trusted partners. Maintaining that strong relationship with your banker will allow him or her to more easily help you plan for the future and offer suggestions to best meet your unique needs.
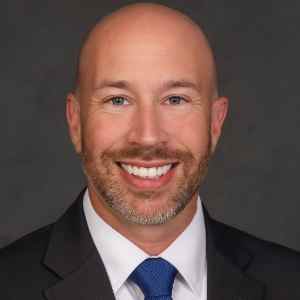
Chris George is senior vice president at PNC Bank and longtime Wilmington resident. He has served PNC and its predecessors for more than 20 years in various leadership roles. PNC Bank, N.A., a member of The PNC Financial Services Group, Inc., is one of the United States’ largest diversified financial services organizations, providing retail and business banking; residential mortgage banking; specialized services for corporations and government entities, including corporate banking, real estate finance and asset-based lending; wealth management and asset management.
These articles are for general information purposes only and are not intended to provide legal, tax, accounting or financial advice. PNC urges its customers to do independent research and to consult with financial and legal professionals before making any financial decisions.