Did you know that by being involved with a business that has employees, you could be held personally liable if the employment taxes are not paid? While the payment of employment taxes is automatically the responsibility of employers operating as sole-proprietors and collectible from the individual owners, the unpaid employment taxes of businesses operating as corporations are the responsibility of the corporation. If the corporation neglects to pay, the Internal Revenue Service has a powerful tool at its disposal, the capability to hold individuals liable for a portion of the unpaid employment taxes of a corporation and to collect from the personal assets of those responsible individuals.
In order to encourage the timely payment of withheld income and employment taxes, Internal Revenue Code Section 6672 created a penalty known as the “Trust Fund Recovery Penalty”. The Internal Revenue Code considers withheld taxes (income, social security, certain excise taxes and railroad retirement taxes) to be “trust fund” taxes as these funds are held in trust for employees until they are paid in to the government by an employer.
If a corporation fails to timely pay trust funds to the government, IRC Section 6672 authorizes the IRS to conduct an investigation to determine whether an individual or individuals might be held personally responsible for the non-payment. This investigation will involve interviews with anyone that may have been in a position to know who held the authority to direct payments and anyone with direct knowledge of the decision-making process of the business. The goal of these interviews is to determine who may have known of the non-payment or was in a position that they should have known of the non-payment and to determine who had the authority to pay or direct payment and did not. Additionally the IRS will often issue a Summons to banks and other record keepers to secure information to further determine potential responsibility. The IRS will review the interview responses and the payroll and bank records and make a determination as to responsibility.
People or groups of people that may be deemed responsible include:


Tech Wilmington: Upcoming Events Calendar
Staff Reports
-
Oct 21, 2026
|
|
Corning Moves Forward With Wilmington Expansion
Cierra Noffke
-
Oct 21, 2026
|
|
Wilmington Startup Joins NVIDIA Inception Program
Cierra Noffke
-
Oct 23, 2026
|
|
Live Oak Bank Reports Q3 Revenue Growth
Cierra Noffke
-
Oct 22, 2026
|
|
Under New Owner, Pour Taproom To Add More Nonalcoholic Beverages, Events
Emma Dill
-
Oct 21, 2026
|
|
A CON law prohibits healthcare providers from building certain medical facilities, developing new health services or acquiring certain medic...
Uncertainty hangs over the hemp industry, including businesses in Wilmington that depend on the sale of hemp-based THC products....
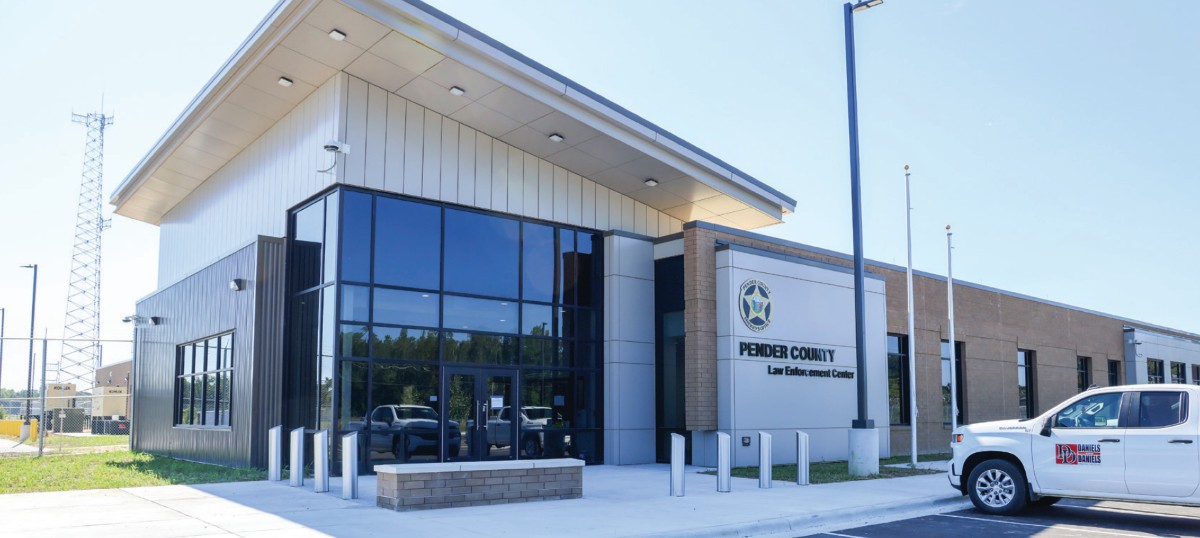
New buildings have opened or will soon open in Burgaw this year to support growing Pender County, including a new law enforcement center and...
The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.