This Insights article was contributed by Sandy Crumrine, CPA.
Public charities depend on donations from private citizens and businesses to continue their good works.
Not all the contributions that keep these organizations running, however, are cold, hard cash. Non-cash contributions, also referred to as “in-kind giving,” are gifts of tangible assets, such as food, clothing, office supplies or medical supplies. Donated goods may be used, surplus, or brand new. In-kind gifts may also be intangible such as advertising or professional services.
In-kind gifts are particularly useful to charitable organizations if they are central to the organization’s mission or free up cash for operating essentials, such as payroll. Beyond revenue and cost savings, many charities find in-kind donations an effective way to cultivate supporters and build capacity.
From the donor’s perspective, in-kind contributions provide an ideal opportunity for corporate donors to be more generous than they might otherwise be. If your philanthropy budget is tight, in-kind gifts may offer a more accessible giving pathway. Donors receive a sense of satisfaction from passing useful items they no longer need on to charities, and many in-kind gifts are tax deductible to the donor.
Pharmaceutical companies are often at the top of the list of in-kind donors, giving away billions of products each year, and tech companies are also commonly generous at in-kind gifts. If you think that you or your company does not have goods or service that are easy to donate, think again. Every company has something to offer when it comes to in-kind giving.
Public charities are required to report all cash and In-Kind gifts above a defined dollar value on Schedule B, Schedule of Contributors, of their annual IRS Form 990, Return of Organization Exempt From Income Tax, including the donor’s name, address, and the amount donated. When an organization receives in-kind gifts of more than $25,000 during the tax year, Schedule M, Noncash Contributions, must be completed listing the number of items received, the value of each, and the method for determining the value.
Although there is no single formula for determining the value of donated goods, the IRS’s Publication 561 is a guide to determining the fair market value (FMV) of donated property. The FMV is the agreed-upon price that the property would sell for on the open market between a willing buyer and seller. In-kind gifts above a certain FMV must be accompanied by an appraisal. Good record-keeping is essential.
Keep the following in mind when considering making an in-kind gift:


Tech Wilmington: Upcoming Events Calendar
Staff Reports
-
Sep 16, 2026
|
|
Leone, Capone Chair This Year's United Way Campaign
Staff Reports
-
Sep 15, 2026
|
|
Singletary Selected To Lead Southport Parks And Recreation
Staff Reports
-
Sep 15, 2026
|
|
Brunswick County Planning Board To Consider 450-home Development Plans
Cierra Noffke
-
Sep 14, 2026
|
|
LS3P Announces New Leadership Roles For Miller, Adams
Staff Reports
-
Sep 15, 2026
|
|
Funded by donations, offerings and grants, Hope Recovery is permanently housed in the former Devon Park United Methodist Church and hosts mo...
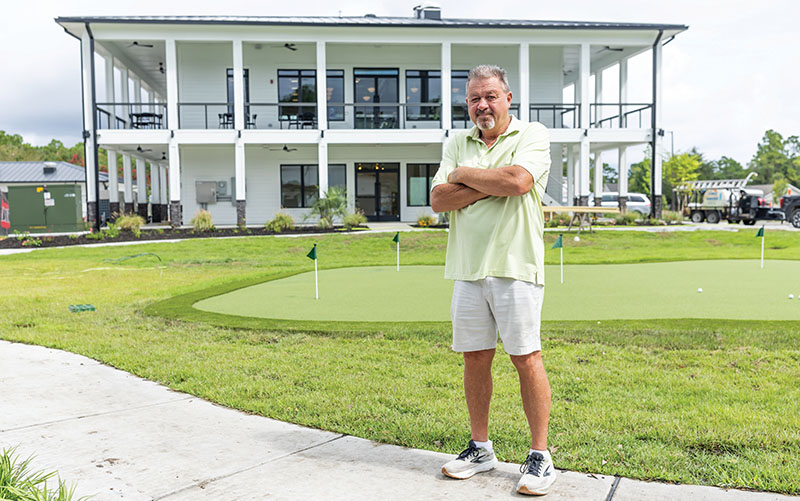
One of the clubs in Wilmington has 11 indoor pickleball courts, four covered, lighted outdoor courts, two new clay tennis courts, an outdoor...
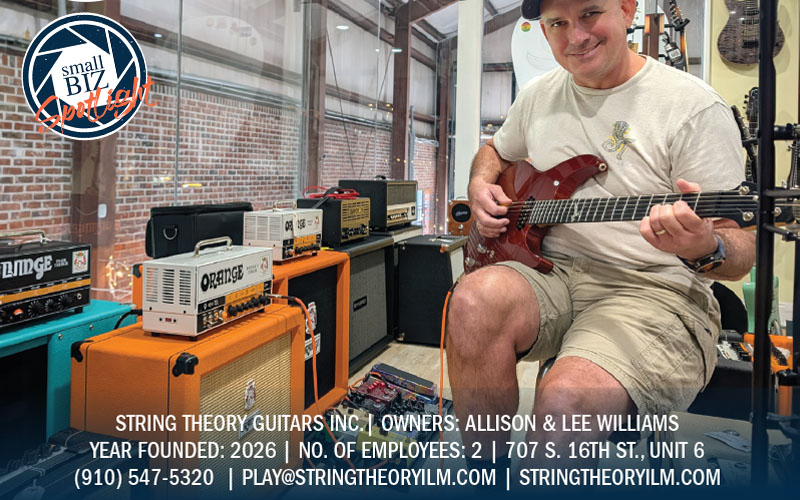
"We love Wilmington and the live music scene here, and we wanted a way to be a part of the music community without having to start work at 9...
The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.