For CPAs, the beginning of fall always represents final deadlines for individual and business returns (calendar year), along with an increased focus on planning and preparing for 2017 filings.
We spend a lot of time with clients this time of year, helping them accomplish their goals for the year, which generally focus on tax minimization and cash flow management.
One of the planning opportunities we always look at is retirement options for clients and how to maximize tax benefits with future distribution goals. One tool available to taxpayers is a form of defined benefit plan commonly referred to as “cash balance plans.”
The difference between a defined benefit plan and a defined contribution plan is really based on who contributes the money to the plan. A defined benefit plan is typically funded by the employer, whereas a defined contribution plan is primarily funded by the employee’s deferral into the plan.
Traditional defined benefit plans are becoming less and less used by employers and governments as they look to shift more of the cost and responsibility to save for retirement onto the employee. However, the use of cash balance plans has been increasing since first introduced in 1985. Sole proprietors or partners in medical, legal and other professional groups are responsible for a majority of this growth.
One aspect that makes a cash balance plan appealing to a small business owner, especially one who is older, is the high contribution levels that increase as you get older. The high contribution limits also offer large tax deductions and, for those who have not been able to put away as much retirement savings, the cash balance plan is a great way to catch up.
Cash balance plans allow for employers to make contributions on their behalf, as well as on behalf of the employees. This is where coordination with your CPA, financial advisor and retirement plan administrator can really pay off.
In our planning for the use of cash balance plans, one of the most heavily weighted factors we use is how much of the contribution is going to the owners. We generally like to see 70 percent of the contribution going to the owners but this can be adjusted based on other goals. So, if a company was eligible to make $100,000 cash balance contribution, we would like to see at least 70 percent go to the owners’ accounts.
Unlike a contribution plan, a defined benefit plan generally provides little or no investment risk for the plan participant. He or she is not impacted by variabilities in the stock market, which adds to the plan’s attractiveness.
Much like in a 401(k) plan, each participant has his or her own account and can actually use the cash balance plan in conjunction with a 401(k) plan. When or if a participant leaves a company, the participant will not lose the amount that has been invested, as long as the participant is vested in the benefit. Upon retirement, participants can take the money as a monthly annuity or roll it over to an IRA.
This article was intended to provide a very broad overview of cash balance plans. If you would like to discuss further please feel free to give us a call and we would be glad to review your situation with you!
Chad Wouters, CPA joined Earney & Company in December 2006 and became the tax partner in November 2013. With an emphasis on strategy and planning, Chad works with his clients all year to ensure the most efficient tax strategies are put into place. Earney & Company, L.L.P. is a CPA firm that handles tax compliance, consulting and planning as well as audit and other assurance services. For more information please visit www.earneynet.com or call (910) 256-9995. Chad can also be reached at [email protected].


Tech Wilmington: Upcoming Events Calendar
Staff Reports
-
Sep 16, 2026
|
|
Leone, Capone Chair This Year's United Way Campaign
Staff Reports
-
Sep 15, 2026
|
|
Singletary Selected To Lead Southport Parks And Recreation
Staff Reports
-
Sep 15, 2026
|
|
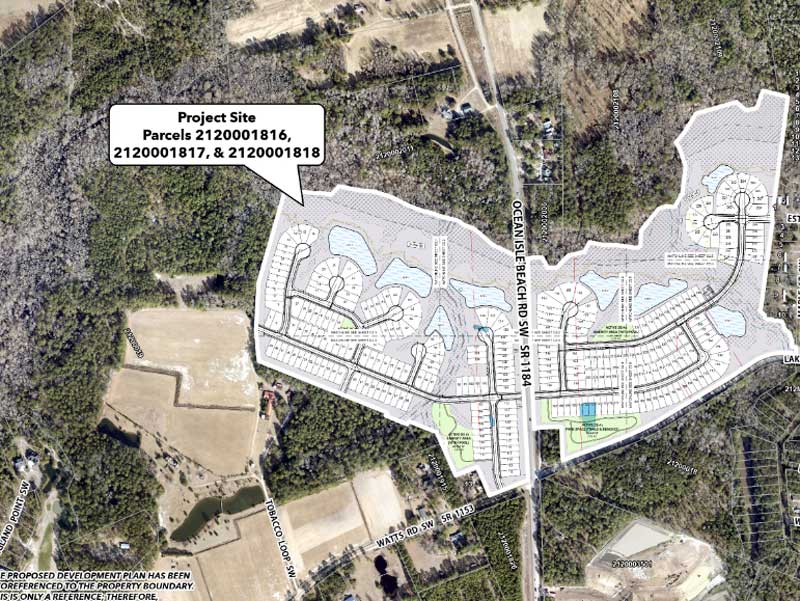
Brunswick County Planning Board To Consider 450-home Development Plans
Cierra Noffke
-
Sep 14, 2026
|
|
LS3P Announces New Leadership Roles For Miller, Adams
Staff Reports
-
Sep 15, 2026
|
|
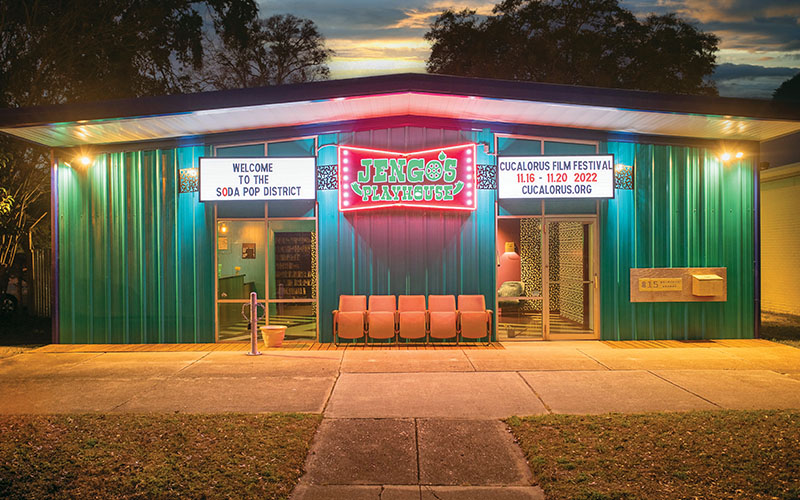
Dan Brawley, head of the Cucalorus Film Festival and founder of Jengo’s Playhouse, recently discussed the venue’s year-round efforts and thi...
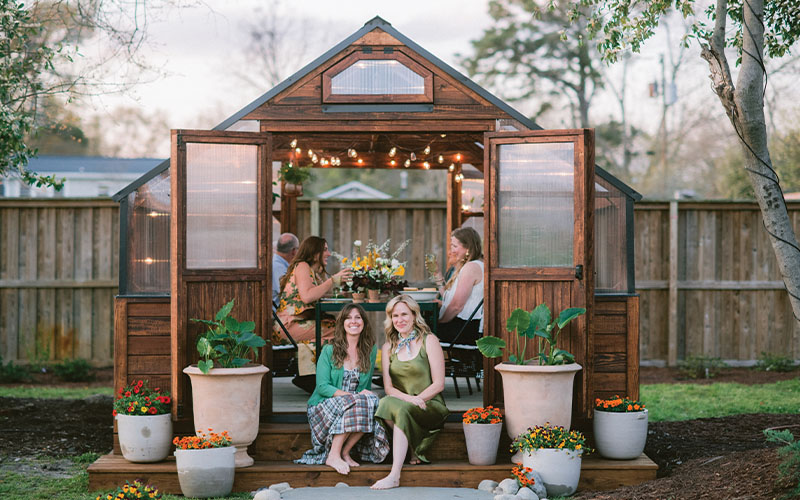
The expanding footprints of Perennial Harbor and Blossom Bay are among the latest examples of growth in the Soda Pop District, which stretch...
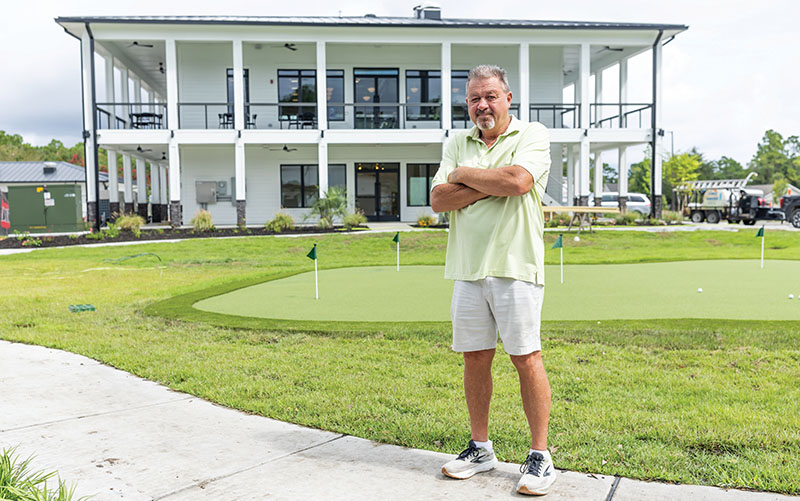
One of the clubs in Wilmington has 11 indoor pickleball courts, four covered, lighted outdoor courts, two new clay tennis courts, an outdoor...
The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.