When I speak to clients about Long Term Care coverage, two prevalent responses I hear are that the premiums are a little too expensive and I will probably end up on Medicaid anyhow while others might say they prefer to self-insure vs paying premiums for something they may never need.
The current average cost of care for the duration of long-term care needs is between $220,000 - $380,000 in a four-year period of need. See my last article “Is long term care right for you” which details some of the average cost and statistics of long-term care. This is out of budget for most retirees so how do we protect these savings and assets regardless of the amount?
Medicaid can certainly bear the burden of the cost of LTC but only after spending down the vast majority of your savings and assets in order to qualify, especially if you are single or widowed. Even primary residences can be affected by spend-down requirements.
This is very troublesome if you want to pass any assets along to your kids. Long-term care insurance provides two key protections. It provides a choice of care and will exclude your savings and assets on a dollar-for-dollar basis from the Medicaid spend-down formula.
This is allowed through the Long-Term Care partnership program which is a state and federal program to incentivize the purchase of LTC insurance. For example, if you were to purchase $180,000 of coverage today at age 55 with a 3% inflation rider and need LTC coverage at age 85 that would be a future pooled benefit of $436,907 directly excluded from the Medicaid spend-down formula.
This means you could qualify for Medicaid with $436,907 of non-exempt savings and assets for yourself or eventually your kids. This is probably the closest you can get to the old saying of “having your cake and eating it too”. For reference, the premium for a similar plan would be about $180/month for a male and $300/month for a female with joint benefit enhancements when applying as a couple.
For those that would prefer to self-insure, I would say there is a better option. If you have plenty of savings and assets to cover the cost of long-term care is that really how you want to spend it?
A better strategy would be to use a hybrid model paying premiums for a limited time such as 10 years to fund the LTC insurance through life insurance in conjunction with a robust LTC rider. Such a policy might have an initial death benefit of $150,000 and a pooled LTC benefit of $432,000 that would grow to over $1,000,000 by age 85. The initial death benefit is also guaranteed for the life of the insured which constitutes a guaranteed return of premium should you never need long-term care.
You can guarantee your long-term care cost never comes out of your hard-earned retirement savings while incurring very little lost opportunity cost of funding the policy. These policies are fully scalable as well for those with smaller budgets or who only wish to partially insure the risk.
In conclusion, whether you are unable to afford LTC if you should need it and would have to rely on the government Medicaid system or if you have successfully saved enough to self-insure the risk, Long Term Care coverage is a smart investment for yourself and your family.


Landfall Home Sale Shatters Community's Previous Price Record
Cece Nunn
-
Nov 9, 2026
|
|
On Oleander Drive, Flaming Amy's Building Listed For Sale, Ground Lease
Emma Dill
-
Nov 10, 2026
|
|
Wilmington Developer Takes First Video Game To Market
Cierra Noffke
-
Nov 10, 2026
|
|
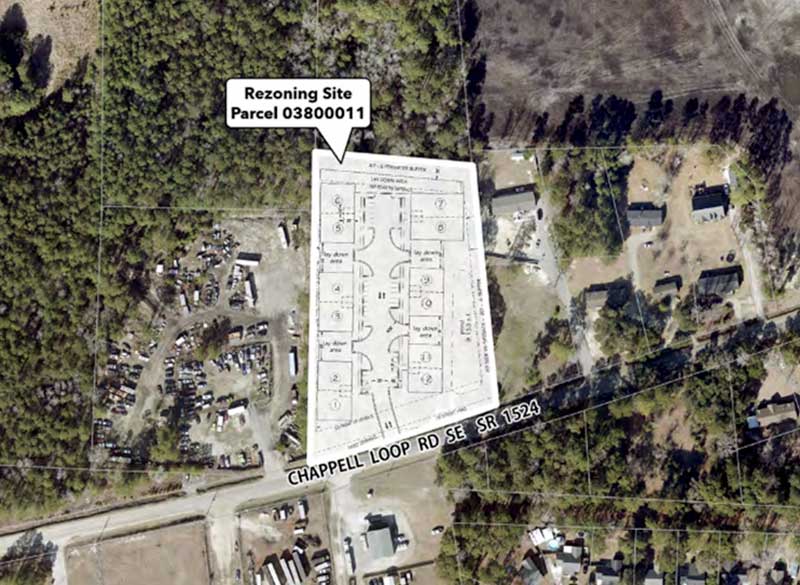
Flex Space Project Pitched Near Leland
Emma Dill
-
Nov 9, 2026
|
|
Paterson Joins Margaret Rudd & Associates Inc. Realtors
Staff Reports
-
Nov 10, 2026
|
|
The 1,400-acre Riverlights master-planned community on River Road in Wilmington welcomed its first residents in 2016. Since then, the commun...
Some businesses use golf simulators to help clients up their game....
While it has evolved countless times over the decades, Wilmington’s downtown remains an attraction in its own right, with historic architect...
The 2026 WilmingtonBiz: Book on Business is an annual publication showcasing the Wilmington region as a center of business.